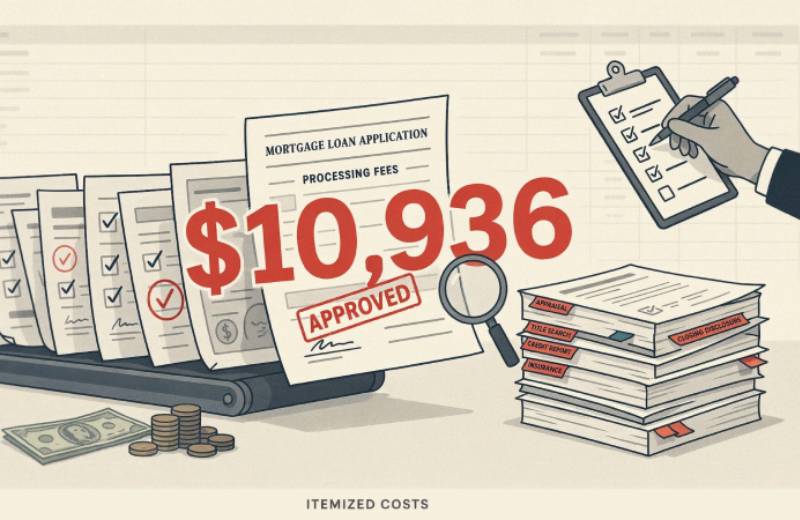

The second quarter looked like good news. Independent mortgage banks and the mortgage subsidiaries of chartered banks earned an average pretax net production profit of $973 per loan, up from $727 in the first quarter, according to the Mortgage Bankers Association’s Quarterly Mortgage Bankers Performance Report. Production expenses fell to 308 basis points from 336. Per-loan costs dropped to $10,936 from $11,898.
Read against the last quarter, that is a recovery. Read against the last two decades, it is not. Since the first quarter of 2008, loan production expenses have averaged $7,903 per loan. The industry just celebrated a number roughly 38 percent above its own long-run average, and the MBA itself noted that quarterly production profits remain below the historical average.
The cost of manufacturing a mortgage did not creep up because lenders got lazy. It went up because the work got heavier and the answer was almost always to add people to it.
The Cost Is Labor, and Everyone Knows It
The MBA’s Peer Group Roundtable data makes the point without much room for argument. In the retail channel in 2025, independent mortgage companies averaged $12,209 to originate a loan, and sales expense accounted for 60 percent of that total. Depositories averaged $16,320, with sales expense at 42 percent and corporate and production support allocations accounting for another 38 percent.
Strip out the accounting language and the finding is simple. A mortgage costs what it costs because of the number of human hours attached to it. Some of those hours are the reason the industry exists. Sitting with a borrower who does not understand why their debt-to-income ratio disqualifies them, or talking a first-time buyer through a rate lock decision, is skilled work that deserves to be paid for.
Most of the hours are not that. They are the fourth request for the same bank statement. They are the status update a borrower asks for at 9 p.m. because the loan is the largest financial commitment of their life and nobody has called them in three days. They are the dormant lead sitting in a CRM that no one has touched in eleven months. That work is real, it has to happen, and it does not require a licensed professional to perform it.
The industry has spent two decades solving this by hiring into every boom and cutting into every downturn. That cycle is what produced a per-loan cost curve that only bends when volume happens to cooperate.
A Different Place to Put the Work
We built Cindie around a straightforward premise. If the expensive part of a mortgage is repetitive communication and administrative follow-through, then that is where automation belongs, and it belongs there as capacity rather than as another dashboard.
Cindie is an AI workforce for residential lending. It engages inbound leads and answers routine mortgage questions outside business hours. It works new and dormant leads, books appointments and routes qualified borrowers to loan officers. It collects application information and chases supporting documentation. It stays in contact with borrowers after the loan closes, which is the point in the lifecycle where lenders most reliably lose future business to whoever calls first.
What it does not do is make lending decisions. Licensed mortgage professionals remain responsible for those, and for compliance. That boundary is not a marketing position. It is a design requirement, and I would argue it is the only defensible way to build in this category right now.
What the Next Cycle Rewards
Volume will move. It always does. The MBA has forecast total single-family origination volume rising to $2.2 trillion in 2026, up from roughly $2.0 trillion in 2025. When it moves, the lenders who staffed for the last cycle will scramble to staff for this one, and per-loan costs will follow the same path they have followed since 2008.
The alternative is to stop treating headcount as the only lever. A lender that can absorb a 30 percent jump in application volume without a corresponding jump in payroll is not simply more profitable. It is more stable, because it is no longer forced to lay off the people it spent a year training every time rates move against it.
That is the version of this business worth building toward. Not one where loan officers are replaced, but one where the job is worth doing again, because the parts of it that nobody became a loan officer to do have been handed to something that never gets tired of asking for a bank statement.
Ben Anderson is the founder and chief executive officer of Cindie, an AI workforce built for the mortgage industry. He also founded Low Rate Co and the mortgage coaching platform Ben Anderson 365, and has originated more than $4 billion in home loans. Connect with him on LinkedIn.